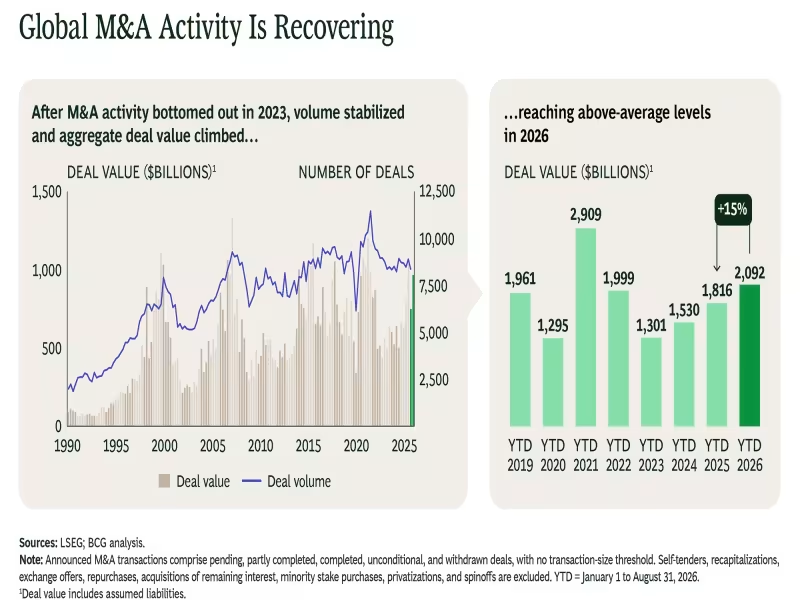
Boston – September 21, 2026 -- Global M&A value climbed 15% year over year in the first eight months of 2026, exceeding the ten-year average by 11%, according to a new report from Boston Consulting Group (BCG). The number of megadeals worth $10 billion or more rose to 37 from 24 a year earlier, surpassing 2021's record of 32.
Megadeal surge masks a narrower recovery below the top of the market
Transactions valued at $1 billion or more are running above longer-term norms, but deal volume for small-cap and midcap transactions remains below historical levels even before inflation adjustments. BCG's M&A Sentiment Index rose to 83 from 79 at the start of the year, still well below its long-term average of 100.
"Capital and strategic appetite are available," said Jens Kengelbach, BCG's global leader of Mergers & Acquisitions and a coauthor of the report. "The bottleneck has shifted to execution: finding transaction-ready assets, bridging valuation gaps, and clearing the operational and regulatory hurdles required to close."
Sentiment diverges sharply across sectors despite overall improvement
Financial institutions and real estate posted the strongest sentiment reading at 108, followed by health care at 100 and energy at 96. Industrials trailed at 66, consumer at 64, and technology at 52. Despite weaker sentiment, technology, media, and telecommunications remained the largest sector by aggregate deal value, up 11% year over year, while consumer deal value rose 20%.
AI drives new deal activity while complicating asset valuation
AI is encouraging fresh investment in parts of the market while adding uncertainty around business model durability and competitive positioning elsewhere, making some assets harder to value and transact. A sharp correction in software company valuations earlier this year, combined with a pullback in private-equity software deal activity, illustrates the effect.
"AI is doing two things to this market at once," said Daniel Friedman, BCG's global leader of Transactions & Integrations and a coauthor of the report. "It's a reason to do more deals and a reason some deals are harder to close."
North America dominates deal value while Asia-Pacific activity declines
North America accounted for more than half of aggregate global deal value. Europe recorded the strongest percentage growth of any major region, while Asia-Pacific activity fell.
Regulatory scrutiny shifts toward national security rather than easing
Conventional antitrust enforcement has softened in parts of the market, but national-security screening, foreign-investment controls, and foreign-subsidy reviews increasingly shape deal terms, timing, and economics.
BCG points to divestitures, carve-outs, and private equity exits as levers that could widen the pool of transaction-ready assets, alongside alternative structures such as minority investments, joint ventures, staged acquisitions, earnouts, and rollover equity to bridge valuation and regulatory risk—particularly among dealmakers in the AI ecosystem.